
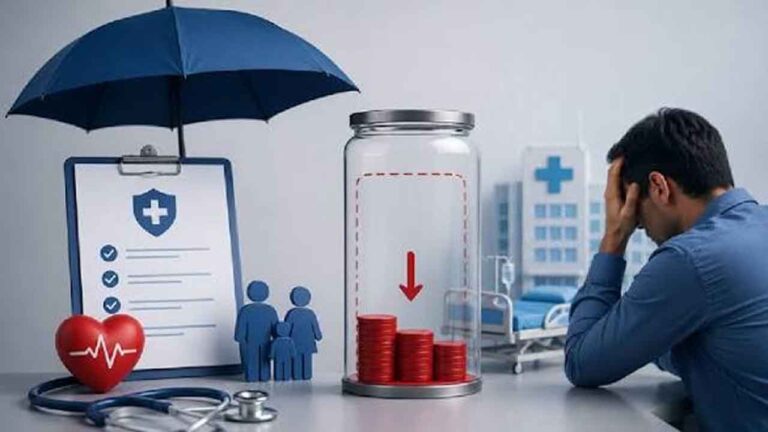
Health insurance can cover eligible medical expenses only up to the amount available under your policy. A large hospital bill, repeated treatment or more than one admission can sometimes use up that amount before the policy year ends.
If this happens, you may wonder whether the policy becomes useless for the remaining months. That is not always the case. Restoration benefits, bonus cover or another active policy may still help, depending on the terms of your cover.
What Happens When Your Sum Insured Runs Out?
Once the available sum insured is fully used, the main cover cannot usually pay further eligible claims during that policy year unless another benefit becomes available. Your policy itself can remain active.
What happens next depends on factors such as:
- Whether restoration cover is included.
- Whether any bonus cover is still available.
- Whether you have another active health policy.
- Whether the next treatment has a separate benefit.
- Whether any policy limits or exclusions apply.
Do You Have to Pay All Further Medical Expenses?
You may have to pay later medical bills yourself when the full sum insured has been used, and there is no additional cover left. For example, if your health insurance 5 lakh cover has been fully used during an earlier hospitalisation, check whether your policy offers any additional benefits that can support a later claim.
These may include:
- A restoration or refill benefit.
- Extra cover earned through a bonus.
- Another personal health policy.
- Employer-provided health cover.
- Any separate benefit that remains unused.
Can You Use a Restoration Benefit?
A restoration benefit can refill the sum insured after it has been partly or fully used. It can help when you need another hospitalisation later in the same policy year.
Before depending on this benefit, check:
- When restoration becomes active.
- Whether full exhaustion is required.
- Whether it covers the same illness again.
- Whether it can be used more than once.
- Whether specific conditions are excluded.
Restoration rules differ between policies, so the wording of your policy matters.
Does a No-Claim Bonus Help Increase Coverage?
A no-claim bonus may increase your available cover after a claim-free policy period. If you had already earned such a bonus before the current year, the added amount may increase the total cover available for claims.
Keep in mind that:
- The bonus may reduce after a claim.
- The full bonus may also get used during treatment.
- The way it works can differ between policies.
- A maximum bonus limit may apply.
Can You Claim Under Multiple Health Insurance Policies?
Yes, if you have more than one active health policy, another policy may help after the available cover under the first one is used. Each claim is still assessed under the terms of the policy used.
Depending on the situation, you may:
- Use one policy for an earlier hospitalisation.
- Use another policy for a later hospitalisation.
- Claim an eligible unpaid portion under another policy where permitted.
- Use personal cover after employer cover is exhausted.
Always keep claim documents and settlement details safe.
Are You Covered for Another Hospitalisation?
Another hospitalisation may still be covered when you have unused cover, restored cover or another active policy. If none of these is available, the exhausted policy may not pay the fresh claim.
Before another admission, check:
- Your remaining sum insured.
- Whether restoration has been activated.
- Whether the treatment is covered.
- Whether any waiting period applies.
- Whether another policy can be used.
This gives you a clearer idea of possible out-of-pocket costs.
Can You Increase Your Sum Insured Mid-Year?
Increasing the sum insured during an active policy year may not always be possible. Many policies allow you to request a higher amount at renewal instead. Any increase can be subject to the policy terms.
Before requesting a change, ask about:
- When the higher cover will start.
- Whether waiting periods apply to the increased amount.
- Whether medical information is required.
- How the premium may change.
Do not wait until a claim happens to understand these conditions.
How Can You Avoid Running Out of Coverage?
You cannot predict every medical need, but planning your cover carefully can reduce the chance of exhausting it too soon.
Useful steps include:
- Choose a sum insured that suits your healthcare needs.
- Check whether restoration is available.
- Understand room rent and treatment limits.
- Track the remaining cover after every claim.
- Review your policy before renewal.
- Keep details of any employer or additional policy handy.
- Read the policy wording instead of relying only on the headline cover amount.
Conclusion
Running out of your sum insured mid-year does not always mean that every form of cover ends. Restoration benefits, bonus cover or another active health policy may still support later medical expenses. The exact position depends on your policy terms and the cover already used. After a major claim, check the remaining balance and available benefits carefully. Doing this early can help you understand what support is still available before another medical need arises.